

rapid! Pay

- 13.77K Reviews
- 4.3
- Downloads
- 1,000,000+
Our take on rapid! Pay from Appgk
Managing a payment card from a phone sounds simple, but the experience depends on whether the app stays understandable when you are in a hurry, dealing with limited vision, using one hand, or trying to complete a task in a noisy place. I spent time with rapid! Pay, the finance app from Green Dot, looking at it from that practical angle rather than treating it as just another card companion. My impression is that it is most useful for people who already use the rapid! card service and want a more convenient mobile point of access, while its value is much lower for someone seeking a complete everyday banking replacement.
The app is free, rated for Everyone, and supports Android devices running version 7.0 or later. It has reached over a million installs, with an average rating of 4.3 from roughly 78 thousand ratings. Those figures suggest that it is an established tool rather than an obscure experiment, although popularity alone does not tell me whether every user will find it comfortable or easy to operate.
How rapid! Pay feels to use in everyday situations
Readability and navigation that favor focused tasks
rapid! Pay is built around a narrow purpose: giving rapid! cardholders a mobile way to interact with their card account. That focus is important. I do not approach it expecting the broad financial dashboard found in a full-service bank app, and I think the experience makes more sense when viewed as a companion for card-related tasks rather than as a complete money-management center.
In practical use, a focused app can be easier to understand because there are fewer unrelated destinations competing for attention. Someone checking a card balance, reviewing recent activity, or trying to handle a card-related task does not necessarily want budgeting charts, investment pages, loan offers, and other banking sections mixed into the same journey. The trade-off is that rapid! Pay may feel limited if you want one application to organize every part of your financial life.
Best Parts of rapid! Pay
Things to Keep in Mind About rapid! Pay
The app’s store summary presents it as a place to register new rapid! cards, while its short description identifies it as a payment-oriented mobile app. That combination tells me that new users should think about setup first: have the physical card and the information needed for registration nearby, and avoid beginning the process when you are rushing to pay for something. Registration is the kind of task where a small typing mistake or a missed instruction can create unnecessary frustration.
I also prefer to approach financial apps with a slower rhythm than social or shopping apps. Before tapping through a confirmation screen, I would read the wording carefully and check that the card or account shown is the one I intended to manage. This is especially useful for people who find dense screens difficult to scan. A deliberate workflow is safer than relying on speed, even when the app itself feels straightforward.
News and Features Related to rapid! Pay

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
For someone with reduced vision, readability is not only about whether text appears large enough. Contrast, spacing, the ability to zoom the device display, and whether labels remain understandable when enlarged all matter. I would recommend testing rapid! Pay with the phone’s own display-size and text-size settings before deciding whether it suits you. Those system tools can make a meaningful difference, but they cannot repair unclear labels or crowded layouts.
Screen readers are another important consideration. I would not assume that every control is perfectly announced simply because the app runs on a modern phone. A user who depends on spoken feedback should open the app with the device’s accessibility service enabled and try the complete path they actually need, including registration and sign-in. If a button is announced vaguely or an error message is hard to locate, that is a serious barrier in a finance app, not a minor inconvenience.
Don't want to read the full review?
Motor and sensory considerations during card management
Mobile financial tasks often involve small targets, text entry, and confirmation steps. That creates different challenges for people with tremors, limited dexterity, joint pain, or difficulty maintaining a steady grip. My practical advice is to use rapid! Pay while the phone is resting on a stable surface whenever possible. That reduces the need to hold the device and tap accurately at the same time.
One useful habit is to separate reading from tapping. I would first review the whole screen, then make one deliberate selection, and pause to check the result. This is slower than rapidly moving through the interface, but it lowers the risk of selecting the wrong option. It is particularly sensible when registering a card or entering account details, because correcting an error may require starting part of the process again.
Screenshots
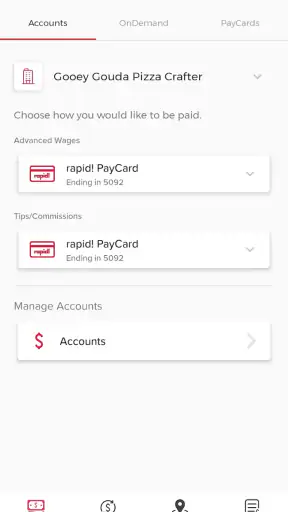
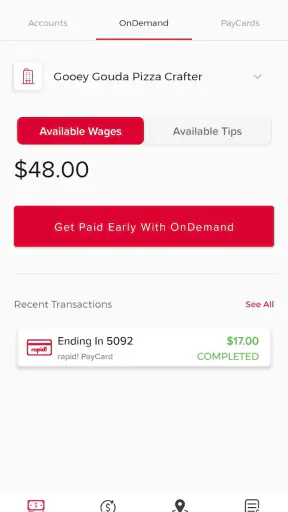
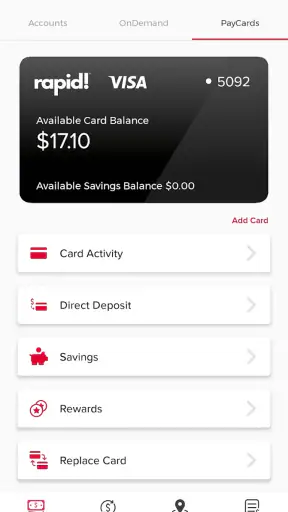
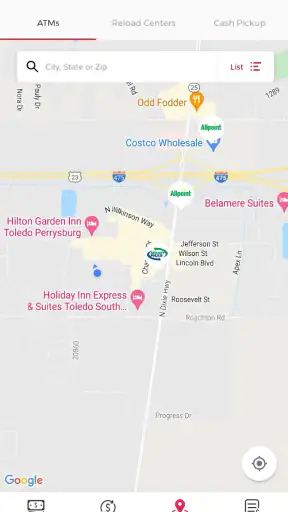
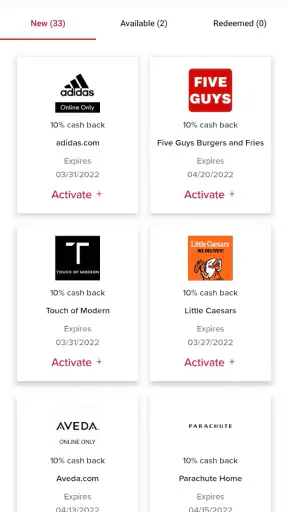
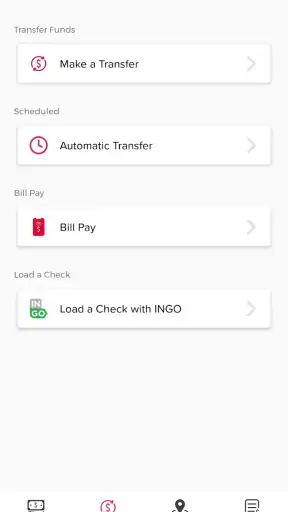
People with sensory sensitivities may also prefer to avoid completing financial tasks in bright, crowded, or noisy environments. A payment app can be technically available while still being difficult to use beside a checkout queue, on public transport, or outdoors in strong sunlight. I find that the best time for setup is at home, with stable lighting and enough time to read every prompt. Once the account is ready, quick checks are less demanding than initial registration.
Voice input can help some people enter text, but I would use it carefully for sensitive financial information. Dictation is convenient for ordinary words, yet card and account details are less forgiving of transcription errors. I would verify every character and avoid speaking private information where other people could hear it. That is not a criticism unique to rapid! Pay; it is a sensible limit for voice-assisted finance workflows generally.
Users who rely on larger touch targets may find that the phone’s accessibility settings are more helpful than changing the app itself. Increasing display size can make controls easier to hit, but it may also cause more scrolling. That trade-off is worth accepting if it improves accuracy. In my view, a finance app should be judged by whether a person can complete important tasks confidently, not by how quickly an experienced user can move through it.
Situational access: when the app is genuinely useful
A realistic example is an employee who receives a rapid! card and wants to register it during a quiet break at home. Instead of waiting to use a desktop computer, the person can use the phone as the main access point and then keep the app available for later card-related checks. This is where the mobile format makes sense: the user is not trying to build a complicated financial plan, only to manage a specific card relationship from a familiar device.
Another situation is a user who travels between workplaces and does not want to depend on a shared computer. A phone-based app can feel more private and convenient, particularly for someone who finds a small mobile routine easier than remembering a separate website workflow. I would still avoid doing sensitive setup over an unreliable public connection or while distracted. Convenience is helpful only when it does not encourage careless confirmation.
The app can also suit people who are comfortable with a phone but less comfortable with traditional banking websites. A familiar mobile device may offer a gentler learning curve than a desktop interface with many menus. This is particularly relevant for older users or anyone who uses a smartphone daily but rarely manages finances online. The best approach is to complete the first session with a trusted helper nearby if assistance is needed, while keeping passwords and personal details private.
For users with changing circumstances, situational access matters. Someone with temporary hand pain may prefer a larger phone, voice assistance for non-sensitive text, and a stable surface. Someone with temporary visual strain may benefit from increased text size and a darker, less reflective environment. rapid! Pay cannot remove every physical or environmental obstacle, but a careful setup can make the mobile workflow more manageable.
Where the app is less suitable is equally clear. If you need detailed spending analysis, automatic budgeting, multiple bank connections, or a broad overview of several financial products, a full banking or personal-finance application will probably serve you better. rapid! Pay’s strength is being tied to rapid! card use, not replacing every financial tool on your phone.
What the app does not solve for every user
Accessibility is not just a matter of adding a larger font. Registration can be demanding for people who have trouble reading small text, remembering credentials, entering long strings, or interpreting security prompts. A person who needs another individual to complete the process may also face privacy concerns. I would prepare the required card and personal information first, choose a quiet setting, and avoid sharing login details even when asking someone for physical help.
Financial apps also carry a higher emotional burden than ordinary utilities. If an error appears, users may worry that money or card access is at risk. Clear recovery steps matter, and uncertainty can be especially stressful for people with cognitive disabilities, language barriers, or limited experience with digital banking. I would not recommend rushing through an unfamiliar message. Take a screenshot only if it does not expose private information, note the exact wording, and use the official support route associated with the card service if the next step is unclear.
Another barrier is device compatibility. The app supports Android 7.0 and newer, which covers many older phones, but a compatible operating system does not guarantee an equally smooth experience on every device. Older hardware may make typing, scrolling, or switching between screens feel less responsive. Before relying on the app for an urgent task, I would install it and complete a low-pressure check while the card information is available.
The current version is 1.0.116, so I would keep the app updated through the normal app-store process when updates are offered. Updates can change layouts or the way a screen is announced by accessibility tools. After an update, users who depend on a particular routine should briefly revisit registration, sign-in, and the main card-management path rather than assuming every control remains in the same place.
There is also a human limitation that no interface can fully remove: a phone is easy to misplace, share, or leave visible. I would use the device’s screen lock, avoid saving sensitive details in plain text, and check the surrounding environment before opening financial information. These precautions may add a few seconds, but they are worthwhile for anyone, especially users who need assistance in public or who frequently lend their phone to family members.
How it compares with familiar alternatives
Compared with a general bank app, rapid! Pay is more specialized. That can be an advantage when the only job is handling a rapid! card, because unrelated banking features are not competing for attention. A bank app is usually the better choice for users who want checking, savings, transfers, statements, and broader financial oversight in one place.
Compared with a mobile browser, a dedicated app can feel more direct for repeat use. You do not need to find the correct page each time, and the experience is designed around the rapid! card relationship. The browser may still be preferable for someone who does not want another app installed, has limited storage, or uses a device where the app feels sluggish. A browser-based route can also be easier for a helper to guide remotely, although privacy still needs careful handling.
Compared with paper records or calling for every routine question, a mobile companion gives users more independence when the phone workflow is comfortable. That independence is valuable, but it should not be confused with universal accessibility. A person who cannot reliably read the screen, enter information, or interpret prompts may find human support more effective for important account tasks.
My main trade-off is therefore specialization versus breadth. rapid! Pay is a sensible fit for a rapid! cardholder who wants mobile access without turning the experience into a full financial command center. It is not the right pick for someone comparing several cards, combining accounts from different providers, or looking for advanced money-management tools.
My inclusive verdict on rapid! Pay
After using it as a focused finance companion, I see rapid! Pay as a practical option for rapid! cardholders who prefer managing card-related needs from a phone. Green Dot has kept the product’s purpose narrow, and that narrowness can help users who become overwhelmed by large banking apps. The free price also makes trying it low risk, while the Everyone age rating reflects its general-purpose financial role rather than a niche audience.
I would recommend setting it up in a calm environment, increasing the phone’s text and display size if needed, testing any screen-reader workflow before depending on it, and using a stable surface for precise taps. Those steps are not substitutes for accessible design, but they can reveal quickly whether the app works with a particular person’s abilities and device.
The strongest reason to choose rapid! Pay is focused mobile access to a rapid! card, not a complete replacement for banking. That distinction should guide the decision. If you want a simple companion for this card and are comfortable checking information on a smartphone, it is worth trying. If you need extensive budgeting, multi-account management, or a workflow that can be completed entirely without visual interaction, I would look at a broader or more specialized alternative instead.
Overall, I find it useful when the user’s needs match its limited but clear role. Its accessibility in real life depends on the phone, the environment, and the person’s preferred way of interacting. For a rapid! cardholder who values independence and can comfortably navigate mobile screens, it may remove unnecessary trips to a computer. For anyone facing significant reading, motor, cognitive, or sensory barriers, I would test the complete task first and keep another support option available.
rapid! Pay FAQ
What is rapid! Pay, and what can I use it for?
rapid! Pay is a mobile payment and money-management app designed for eligible rapid! payroll card users. After installing it, users can typically review their available balance, monitor recent transactions, locate surcharge-free ATMs, and manage certain card settings from their phone. Its exact features may depend on the card program, employer, account type, and country, so check the official terms before relying on it for a specific payment or banking service.
How do I sign in to rapid! Pay for the first time?
To begin using rapid! Pay, you generally need an active rapid! payroll card or eligible account and the personal information requested during registration. The app may ask you to verify your identity, create login credentials, and confirm a phone number or email address. Use only the official app-store listing, keep your login details private, and contact rapid! support if registration fails or your information is not recognized.
Can rapid! Pay be used to make purchases or transfer money?
rapid! Pay is primarily intended to help eligible cardholders manage their rapid! account and card rather than replace every traditional banking application. Depending on your program, you may be able to view transactions, control card functions, or access related payment services. Availability can vary, and some transfers or payments may involve limits, verification requirements, processing times, or fees. Review the in-app disclosures before confirming a transaction.
Are there fees for using rapid! Pay?
Downloading or using the rapid! Pay app itself may not involve a separate app fee, but the associated rapid! card account can still have charges for particular services. Possible costs may include out-of-network ATM withdrawals, expedited services, replacement cards, international transactions, or other program-specific actions. Fees and limits can change, so consult the current fee schedule in the app or on the official rapid! website before using a feature.
Is rapid! Pay safe, and what should I do if my phone or card is lost?
rapid! Pay includes account-security measures such as login protection and identity verification, but users should still enable their phone’s passcode or biometric lock and avoid signing in on shared devices. Never disclose one-time codes or passwords. If your phone or rapid! card is lost, contact the official rapid! support channel immediately, secure access to your account, and request that the card be frozen or replaced if necessary.













